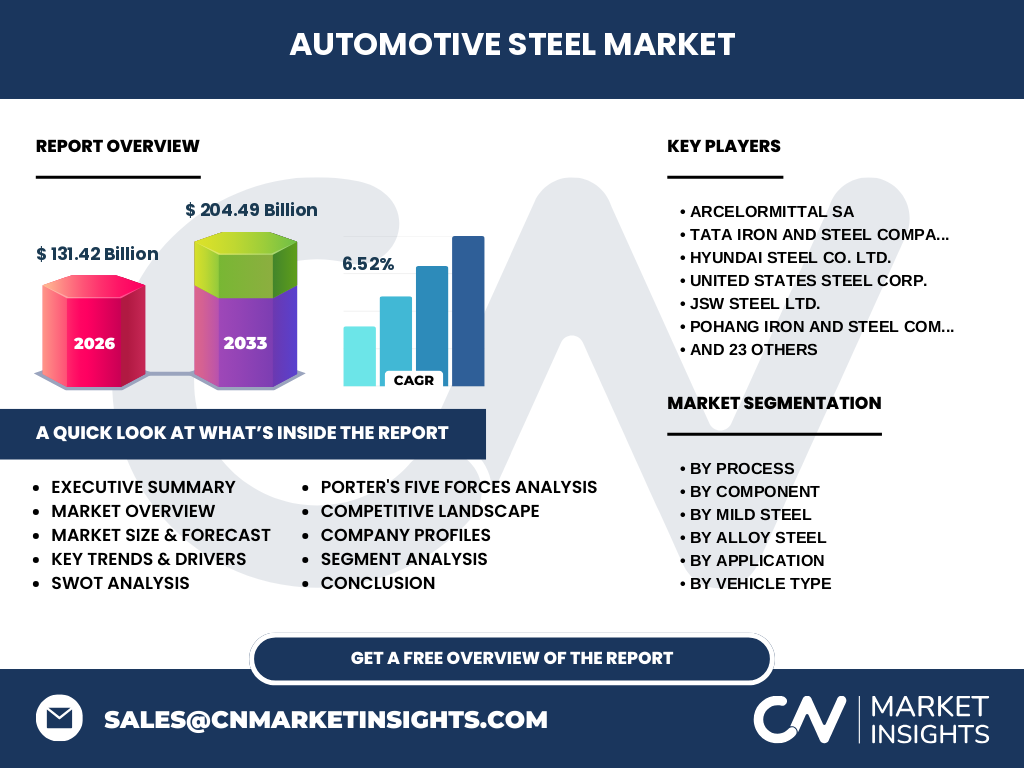
Market overview of the Automotive Steel Market
The Automotive Steel Market is valued at USD 131.42 Billion in 2026, representing a foundational sector for global vehicle manufacturing. Our analysis indicates that steel remains the backbone of chassis, body-in-white, and powertrain architectures despite multi-material competition. Industry significance lies in balancing crash safety mandates with cost-effective mass production across original equipment manufacturers.
Structural Growth Drivers and Restraints in the Automotive Steel Market
Structural growth drivers include stringent crashworthiness regulations by bodies like the NHTSA and IIHS, forcing reliance on Advanced High Strength Steel. Conversely, primary market restraints involve volatile raw material expenses for iron ore and coking coal, alongside the continuous threat of aluminum and carbon fiber substitution in premium electric vehicle platforms.
Emerging trends and growth patterns in Automotive Steel Market
The industry is pivoting heavily toward Electric Arc Furnace (EAF) decarbonization technologies to meet Scope 3 emission targets. Based on our research, major steelmakers like ArcelorMittal SA and Nippon Steel Corporation are prioritizing green hydrogen reduction processes to supply sustainable, low-carbon grades to forward-looking automotive supply chains.
COVID-19 impact analysis and recovery trajectory
The pandemic caused unprecedented supply chain fractures and semiconductor shortages, severely depressing baseline demand within the Automotive Steel Market. The recovery trajectory, however, has been propelled by robust post-lockdown pent-up demand and accelerated regionalization of supply chains, insulating producers against future maritime logistical bottlenecks.
Competitive Benchmarking and Market Concentration
The Competitive landscape is characterized by high market concentration among multinational giants like China Baowu Steel Group, Tata Steel, and POSCO. Strategic dynamics focus on securing captive raw material assets, expanding high-margin Advanced High Strength Steel portfolios, and entering joint ventures with tier-1 automotive stampers to lock in long-term supply agreements.
Executive summary of the Automotive Steel Market
Our comprehensive Automotive Steel Market analysis highlights robust expansion, projecting a market size of USD 204.49 Billion by 2033, growing at a solid 6.52% CAGR from 2027. This momentum is anchored by relentless vehicle lightweighting demands and surging emerging market passenger vehicle production.
Long-term market forecast from 2027 to 2033
Our forecasting models indicate that the Automotive Steel Market industry trends will accelerate post-2027, driven by massive re-tooling for electric vehicle platforms requiring specialized crash-management steels. This expansion will consistently scale the valuation from the 2026 baseline toward the 2033 target through sustained demand in emerging economies.
Segmentation analysis across processes, components, and applications
The Automotive Steel Market segments by process into Basic Oxygen Furnace (BOF) and Electric Arc Furnace (EAF). Component categories span Mild Steel, Alloy Steel, High Strength Steel, and Advanced High Strength Steel (including TRIP and Martensitic grades), deployed across Body Structure, Powertrain, and Suspension systems in Passenger and Commercial Vehicles.
Geographic distribution and regional market performance
Regional performance is heavily anchored by Asia-Pacific manufacturing hubs, where industrial giants like JSW Steel and Hyundai Steel command extensive domestic supply chains. Meanwhile, North American and European markets exhibit mature demand curves focused increasingly on high-grade decarbonized steels to comply with strict regional environmental policies.
In-depth regional review of key manufacturing corridors
The Asia-Pacific region dominates consumption volume due to dense automotive clustering in China, India, and South Korea, supported by entities like China Steel Corporation and Baosteel. In contrast, North American corridors, bolstered by United States Steel Corp. and Nucor, prioritize localized, scrap-fed EAF production to curtail cross-border carbon border adjustment tariffs.
Company profiles and strategic positioning of leading participants
Leading players like Thyssenkrupp Steel Europe AG and JFE Steel Corporation leverage advanced metallurgical expertise to supply tailored laser-welded blanks. Meanwhile, firms like Gerdau S.A. and Jindal Steel and Power Limited optimize regional supply footprints to capture rising infrastructure and commercial vehicle demand.
Porter's Five Forces analysis of the sector
Bargaining power of buyers remains moderately high due to consolidated automotive OEM purchasing conglomerates. Supplier power fluctuates with coking coal and scrap metal availability, while threat of substitutes is perpetually driven by lightweight aluminum alloys in hood and closure panels.
SWOT analysis for the Automotive Steel Market
Strengths include unmatched tensile strength-to-cost ratios and established recycling loops. Weaknesses involve high carbon intensity during virgin ore reduction. Opportunities lie in green steel commercialization, while threats stem from aggressive regulatory push for net-zero supply chains.
Value chain analysis from raw materials to end-users
The value chain originates with raw material extraction of iron ore and metallurgical coal, progressing through primary smelting and refining via BOF or EAF routes. Transformation involves hot-rolling and cold-rolling processes before tier-1 stamping facilities shape components for final automotive assembly lines.
Investment insights and high-potential areas
Strategic investment should target greenfield Electric Arc Furnace installations and hydrogen-based direct reduced iron (DRI) facilities. Capital allocation toward proprietary Advanced High Strength Steel grades yields superior margins amid tightening global vehicle crash safety standards.
Conclusion and core takeaways
The Automotive Steel Market report overview confirms that steel remains indispensable to global mobility, successfully adapting to sustainability pressures. Firms that aggressively green their production portfolios while mastering complex AHSS metallurgy will dominate the 2027-2033 forecast horizon.
Research methodology for baseline estimation
Our baseline estimates are rigorously triangulated by combining official trade registry data, primary stakeholder interviews with chief metallurgists, and secondary macroeconomic indicators from international steel associations. This multi-tiered validation guarantees precise quantitative forecasting.
Scope of the report and coverage parameters
This report encompasses the global Automotive Steel Market market size across specified process routes, micro-alloying components, and vehicle classifications from 2026 through 2033. Excluded from this specific scope are non-automotive structural steel applications and aftermarket repair components.
Recent developments in partnerships and strategic moves
Recent industry momentum features landmark cross-border supply agreements and joint ventures aimed at deploying carbon-neutral steel. Major market makers are actively acquiring scrap-processing scrap yards to secure sustainable metallic inputs ahead of impending carbon tax implementations.